Français
 English
Retiring to Spain from the UK or US: the complete guide
Retiring to Spain gives you a lower cost of living than in the UK, the US or most of northern Europe, a high-performing health system and a varied climate. EU citizens need no visa, while British and American retirees need one, usually the non-lucrative visa, to stay more than 90 days in any 180. Private pensions are generally taxed in Spain, and UK State Pension recipients can use the S1 form for healthcare. The choice of town depends mainly on budget, healthcare and transport.
1. Why retire to Spain?
Retiring to Spain means a change of scene while staying a short flight from the UK and northern Europe. The climate, the general price level and the large British and international communities explain its appeal. The move still needs serious preparation: costs vary widely between regions, there is a lot of paperwork and access to healthcare must be arranged before you leave.
Spain comes out as a balanced destination in our comparison of the best countries to retire abroad, but it does not suit every profile in the same way.
Climates for different lifestyles
Spain has very different climates from one area to another. The Mediterranean coasts and the south generally have mild winters and hot summers, while the north has a wetter, temperate climate. The centre of the country has bigger temperature differences between winter and summer.
So the choice of region should take into account how you cope with heat, humidity and wind, and whether you want to live near the sea. Someone looking for moderate temperatures all year will not necessarily choose the same place as a retiree drawn to very hot summers.
The climate averages published by AEMET (Spain's weather agency) let you compare temperatures and rainfall across regions. They are more reliable than general promises of “sunshine all year round”.
A lower cost of living in Spain
The cost of living is lower overall in Spain, but the gap depends heavily on where you live and how you spend. In 2025, the general price level in Spain was about 8.5% below the EU average.
This national average needs some nuance, though. Housing in Madrid, Barcelona, Málaga or some seaside resorts can weigh heavily on the budget. By contrast, medium-sized towns and places away from the most touristy areas are often more affordable.
Housing, food, transport, leisure and healthcare should therefore be compared one by one. Our article on the cost of living in Spain looks at each of these spending items in more detail. Source: Eurostat, comparative price levels 2024
Monthly budget
A 2025 INE household budget survey provides an official benchmark. In 2025 in Spain:
- average spending was €14,066 per person per year, or about €1,172 a month;
- a household of one person aged 65 or over spent on average €23,024 a year, or about €1,919 a month;
- average spending per person ranged from €12,197 a year in Andalusia to €16,124 in the Community of Madrid.
These amounts are neither a minimum nor a budget recommendation, but they give an idea of the budget.
Property prices in Spain
The Spanish property market has risen sharply since 2023. In August 2026, the average asking price of homes for sale reached €2,924/m² in Spain, up 12.5% in a year. The average asking rent was €15.10/m² a month, up 5.8% year on year.
The differences between cities remain considerable:
- in Madrid, the asking sale price reached €6,471/m² and rent €23.30/m² a month in August 2026;
- in Torrevieja, the sale price was €2,553/m² and rent €12.80/m² a month.
As a rough guide, a 60 m² home would have an asking rent of about €1,398 a month in Madrid, against €768 in Torrevieja. These calculations do not take into account the condition of the home, its neighbourhood, how close it is to the sea or service charges.
As in most countries, housing is the largest household expense in Spain. So it is the first thing to look at before moving. Why not consider buying a flat or a house in Spain to spend your retirement there? At Alveo Search, we help hundreds of retirees every year with their move and their new life.
Day-to-day spending
In 2025, the general price level of household consumption was 91.5 in Spain, against 100 for the EU average. The gap is therefore 8.5 index points. In other words, prices in Spain were about 8.5% below the EU average.
To compare each item, read our article on the cost of living in Spain.
Close to the UK and northern Europe, a real advantage
Being close makes regular trips home easier and limits the break with family and friends. Many Spanish airports have direct flights to the UK and northern Europe, so British and other European retirees avoid the constraints of moving to another continent. American retirees can count on direct flights from Madrid and Barcelona to the United States.
This easy access is especially useful when you need to:
- visit family;
- go back for an administrative procedure;
- keep some appointments in your home country;
- easily host your children or grandchildren;
- split your year between the two countries.
Spain uses the euro and is part of the European Union. For EU retirees, this makes many practical aspects of the move simpler, while British and American retirees have more formalities, especially for residence. In every case, residence, health and tax formalities need to be planned properly as part of a move to Spain.
A well-established expat community
Spain's National Statistics Institute counted 266,462 residents with British nationality on 1 January 2025, all age groups combined. Source: INE, annual population census 2025
English-speaking associations, international schools, services and professionals are found in several large cities and tourist areas. This community can make the first months easier, especially for finding people who know the procedures between Spain and your home country.
It should not mean staying only among English speakers, though. Learning basic Spanish remains important for everyday formalities and for fitting into local life.
The quality of life
International indicators put Spain in a favourable position for life satisfaction and health. In 2024, people in Spain rated their overall life satisfaction at 7.2 out of 10, according to Eurostat. Source: Eurostat, life satisfaction in 2024
Life expectancy also reached 84 years, 2.9 years above the OECD average. Spain also scored better than the OECD average on several indicators of access to care and quality of care. Source: OECD, Health at a Glance 2025.
These results show Spain's many strengths for enjoying your retirement to the full: a pleasant pace of life, accessible services and plenty of ways to stay active and keep up a social life.
What drawbacks should you plan for?
The main drawbacks are price differences between regions, intense heat, the language barrier and the administrative, tax and medical formalities. Spain can offer a pleasant daily life, but the plan needs to be judged on more than the climate and the price of restaurants.
Several points deserve particular attention:
- housing has become expensive in some big cities, on the islands and in popular coastal resorts;
- summers can be hard to bear in the centre and south of the country;
- the administration works in Spanish and some procedures are handled by the autonomous communities or town halls;
- healthcare habits and the organisation of the health system differ from what you know at home;
- tax depends on your residence and the type of pension you receive;
- living far from family can become harder with age;
- seaside towns can be very lively in summer and much quieter out of season.
These limits do not make the plan less worthwhile, but they need to be weighed against the advantages.
2. What paperwork do you need to retire to Spain?
EU retirees can settle in Spain without a visa. British and American retirees can stay up to 90 days in any 180-day period without one, but need a visa to live there, usually the non-lucrative residence visa. In all cases, to live in Spain for more than three months you must register your residence, have sufficient resources and prove you have health cover. Other formalities concern the NIE, the empadronamiento, how your pension is paid and the authorities of your home country.
No visa for EU retirees
Citizens of the European Union, the European Economic Area and Switzerland, such as Irish, German or Dutch nationals, do not need a visa to enter and live in Spain.
For a stay of more than three months, however, a retiree with no professional activity must be able to show:
- sufficient resources for themselves and their family members;
- public or private health insurance covering risks in Spain;
- a valid identity card or passport.
These conditions then allow you to apply for the registration certificate as a citizen of the European Union. Source: Spanish administration, residence rules updated in July 2026
The NIE, the empadronamiento and the residence certificate
These three formalities are often confused, although they do not serve the same purpose.
- The NIE, or Número de Identidad de Extranjero, is a personal number given to foreigners with economic, professional or social interests in Spain. It is used in particular to buy property, for some tax procedures and to set up services. The NIE is an identifier: on its own, it is not a residence permit or proof of residence.
- The empadronamiento is registration on the register of residents of the town where you live. The padrón proves your Spanish address and may be requested for various local formalities.
- The EU citizen registration certificate proves that you are on the Central Register of Foreigners when you live in Spain for more than three months. You apply with form EX-18 and pay fee 790, code 012. British and American retirees who arrive with a visa apply for a foreigner's identity card (TIE) instead.
For the detailed steps, see our guide to the NIE in Spain, in addition to our guides to the empadronamiento and to the residence card in Spain.
The non-lucrative residence visa for British, American and other non-EU retirees
Retirees who are not nationals of an EU country, the European Economic Area or Switzerland, which includes British and American retirees, must get a suitable visa before settling in Spain for the long term.
The non-lucrative residence visa is the most common route for someone with sufficient income who does not plan to work in Spain. It lets you live in the country without working.
Applicants must provide, in particular:
- a national visa application form;
- a valid passport;
- proof of regular and sufficient resources;
- health insurance that meets Spanish requirements;
- a medical certificate;
- a criminal record certificate where required;
- documents translated or legalised as required by the applicable rules.
The minimum level of resources required is 400% of the IPREM for the main applicant, plus an amount for each family member. The exact conditions must be checked with the Spanish consulate that covers where you live, as the documents and how to submit them can change.
Note: buying a home no longer gets you a “golden visa” in Spain. The investor residence scheme was abolished with effect from 3 April 2025.
Our guide to the different visas for Spain helps you find the options that fit each situation.
What to do in your home country before you leave
Before moving to Spain for your retirement, it is advisable to inform the relevant bodies in your home country and gather the documents you will need after the move.
The main steps are:
- give your new address to your pension providers (for the UK State Pension, the International Pension Centre);
- check how your pension can be paid into a home-country or Spanish bank account;
- if you receive a UK State Pension, ask NHS Overseas Healthcare Services for an S1 form;
- tell your tax authority that you are leaving (in the UK, HMRC, usually with form P85);
- keep your pension statements and records of your working life;
- check that your passport or identity card is valid;
- arrange, if needed, to transfer or register your vehicle.
A pension provider may also ask you for a life certificate to keep paying your pension abroad. For the UK State Pension, the Department for Work and Pensions may send you a life certificate form: it must be signed by a witness and sent back, or payments may be suspended.
Registering with your country's consulate
Consular registration is generally voluntary, but some countries offer it to citizens living abroad. US citizens, for example, can enrol free of charge in the State Department's Smart Traveler Enrollment Program (STEP) to receive alerts from their embassy and be reached in an emergency. Ask your embassy or consulate what it offers, for example for renewing documents or voting from abroad.
The exact order of the steps may vary by province, town, nationality and family situation. It is therefore best to check the documents required with the relevant office or police station before each appointment.
3. How do UK and US pensions work when you live in Spain?
You can receive your UK State Pension or US Social Security benefits while living in Spain. If you have also worked in Spain, your contribution periods can be taken into account to establish your rights, but each country calculates and pays its own share of pension under its own rules.
Having your pension paid in Spain
Moving to Spain does not take away the pension rights you built up at home. A UK State Pension can be paid into a bank in Spain or a bank or building society in the UK, and it still increases every year when you live in Spain, as in the rest of the European Economic Area.
After moving, the retiree must in particular:
- give their new address to their pension providers;
- send their new bank details if they want to change account;
- reply to any request for a life certificate;
- tell their pension providers about any change in their situation.
A life certificate lets pension providers check that a beneficiary living abroad can keep receiving their pension. When one is requested, follow the instructions of your pension provider. The country where the pension is paid does not, on its own, decide where it is taxed. Tax residence and the type of pension are covered separately in our guide to tax for retirees in Spain.
Retirement age in Spain in 2026
In 2026, the legal retirement age in Spain depends on how long you have contributed:
- it is 65 for people with at least 38 years and 3 months of contributions;
- it rises to 66 years and 10 months when that contribution period is not reached.
From 2027, the Spanish legal age is set to rise to 67 for people who do not have at least 38 years and 6 months of contributions. This age applies to rights built up in the Spanish system. A retiree who has only worked in the UK or the US claims their pension under that country's rules, even if they then choose to live in Spain.
On the other hand, someone who has contributed in both countries may start receiving their pensions on different dates. Each share is paid when the age and conditions set by the country concerned are met.
Counting periods worked in your home country and in Spain
Periods worked in Spain and in your home country are not lost. For EU citizens, European coordination rules allow them to be added together when checking whether someone has the minimum period needed for a pension. Contributions paid in the EEA, Spain included, can also count towards the conditions for a UK State Pension, and the United States has had a social security agreement with Spain since 1988.
This totalisation does not mean that Spanish contributions are converted into home-country contributions or transferred there. The two systems remain separate:
- your home country keeps the periods completed under its system;
- Spain keeps the periods completed under its system;
- each country takes into account the career completed in the other country when it is needed to establish the right;
- each country only pays for the part of the career that falls under its own system.
Even a period of insurance of less than a year in an EU country is not normally lost. Special rules allow it to be taken into account by the other countries where the person has worked.
The average pension in Spain
In August 2026, the average retirement pension in the Spanish system reached €1,574.90 a month, up 4.5% in a year. The average was:
- €1,733.70 for former employees under the general scheme;
- €1,062.10 for former self-employed workers;
- €976 for widows' and widowers' pensions.
These amounts are neither a minimum pension nor what someone who has worked in Spain will automatically receive. The individual amount depends on the earnings on which contributions were paid, the length of the career and the retirement age.
4. How are UK and US retirees taxed in Spain?
A retiree who becomes tax resident in Spain must generally declare all their income in Spain, including pensions from abroad. Where a pension is taxed depends on its type and on the tax treaty between Spain and the paying country. Private pensions are in principle taxable in Spain, and so is the UK State Pension, while government service pensions often remain taxable in the paying country and US Social Security can also be taxed by the United States.
Tax residence, the starting point
Whether or not you are retired, Spanish tax depends on one key criterion: the taxpayer's tax residence. The law is very clear on this point. A Spanish tax resident is
- anyone who spends more than 183 days in total, not necessarily in a row, per year in Spain;
- anyone whose economic and/or family interests are in Spain.
Spain also has tax treaties with the UK, the US, Ireland, Germany and the Netherlands, among others, which prevent double taxation. In practice, this means you do not pay tax twice on the same income. To find out more, read our interview with Felix de la Guia Muñoz, a Spanish lawyer specialising in tax and property law. When you become tax resident in Spain, tell the tax authority of your home country. US citizens remain subject to US tax on their worldwide income wherever they live, so they keep filing a US return.
The UK-Spain double taxation convention
The UK and Spain have a tax treaty that shares out between the two countries the right to tax each type of income.
For pensions, it mainly provides that:
- private pensions paid to a resident of Spain are taxable only in Spain;
- the UK State Pension paid to a resident of Spain is also taxable in Spain;
- UK government service pensions, for example those of former civil servants, generally remain taxable only in the UK.
The convention avoids double taxation by allocating the right to tax or through tax credits. It does not necessarily remove filing obligations in either country. Source: UK-Spain double taxation convention (2013), GOV.UK
For American retirees, the US-Spain tax treaty provides that private pensions are taxable in the country of residence, while US Social Security benefits may also be taxed by the United States. In all cases, US citizens remain liable to US tax on their worldwide income. Source: US-Spain income tax treaty, IRS
Spanish tax rules, filing thresholds and rates can change. A situation with several pensions, rental income or assets spread between two countries therefore deserves a personalised check.
Find the procedures and special cases in our guide to tax in Spain for retirees.
Tax for retirees who are tax resident in Spain
If you decide to live in Spain permanently in retirement, you will generally be considered a Spanish tax resident. Here is what to remember:
- Your pension is taxable income. Private pensions and the UK State Pension are in principle taxable in Spain when the person receiving them is tax resident there.
- Pensions from former UK government service generally remain taxable in the UK. The main exception is when the pensioner lives in Spain and has Spanish nationality.
- You must also declare your other income in Spain, including rent, investments and any capital gains, subject to the provisions of the tax treaty between Spain and your home country.
Our editorial team has written a full practical guide to IRPF, Spanish income tax.
There are thresholds below which filing an IRPF return is not always compulsory. For 2025 income declared in 2026, the main thresholds are:
- €22,000 of annual income when it comes from a single payer, or when the amounts paid by the second and later payers do not exceed €1,500 in total;
- €15,876 when income comes from several payers and the amounts paid by the second and later payers exceed €1,500;
- €15,876 when the payer is not required to withhold tax in Spain, which can apply in particular to a pension paid from abroad;
- €1,600 for certain investment income and capital gains subject to withholding or a payment on account.
Note: these are thresholds that decide whether you must file a return, not general tax exemptions. Other income, the type of pension or your personal situation can make a return compulsory. The thresholds may also be revised every year. They can be checked in the official filing conditions published by the Agencia Tributaria.
Our advice: a retiree's tax position in Spain can quickly become complex, especially with several pensions or with income and assets kept in the home country. Spanish taxpayers often use a gestor or a tax adviser. If you are looking for trusted professionals, you can contact our team.
Tax for non-residents
If you remain tax resident in your home country but own a second home in Spain, you will be liable for several Spanish taxes linked to buying, owning or selling the property.
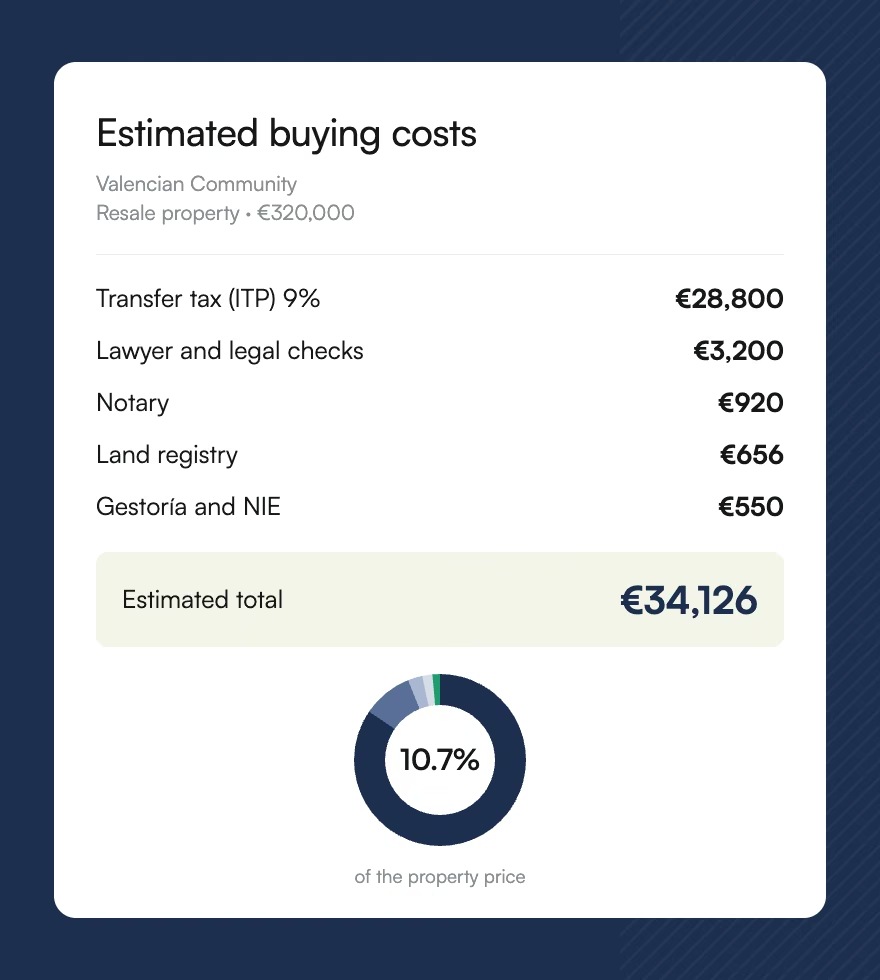
- ITP, or property transfer tax, is paid when buying a resale home. Its rate depends on the autonomous community, the price and any reductions. For a new home bought from a developer, the buyer generally pays Spanish VAT (IVA) and AJD instead of ITP.
- IBI, or property tax, is Spain's local property tax. It is paid every year to the town hall. Its amount depends mainly on the cadastral value of the home and the rate set by the council.
- IRNR, or non-resident income tax, applies in particular to rental income from a property in Spain. The rate is generally 19% for residents of the European Union, Iceland, Norway and Liechtenstein, against 24% for other taxpayers, including residents of the UK and the US.
- The renta imputada applies to homes that are not rented out, or only for part of the year. The tax office then calculates a notional property income, usually 1.1% or 2% of the cadastral value. This percentage is used to set the taxable base: it is not the final tax rate.
- A capital gain on property can be taxed in Spain when you sell the property for more than you paid for it.
- The plusvalía municipal is a municipal tax that may apply when urban land changes hands, in particular through a sale, a gift or an inheritance. It is based on the increase in the value of the land, not of the building. Our guide to property taxes in Spain details the taxes to expect when you buy, while you own the home and when you sell it.
- The Impuesto sobre el Patrimonio, or Spanish wealth tax, may apply to a non-resident with substantial assets in Spain. The general allowance is €700,000 where the applicable rules do not set another, but thresholds, reductions and reliefs vary between autonomous communities.
Inheritance tax
The Impuesto sobre Sucesiones y Donaciones can apply to people living in Spain who receive an inheritance, and also to non-resident heirs when the estate includes assets in Spain.
The EU Regulation No 650/2012 provides that the civil law applying to the whole estate is, in principle, that of the country where the deceased was habitually resident at the time of death. A British or American national living in Spain can, however, state in their will that their estate should be governed by the law of their nationality.
This choice concerns in particular how the estate is shared and the heirs' rights. It does not let you choose the country where inheritance tax is paid: tax rules remain separate.
The amount of Spanish tax depends mainly on:
- the relationship between the deceased and the heir;
- the net value of the assets passed on;
- the heir's existing wealth;
- the autonomous community whose rules apply.
Some autonomous communities give very large allowances or reliefs to spouses, children and other close heirs. These advantages are not, however, a general exemption granted to all residents of the European Union, and their conditions vary by region.
The inheritance tax return must normally be filed within six months of the death. An extension of six more months can be requested, provided the request is made in the first five months. These deadlines are confirmed by the Agencia Tributaria for form 650.
Given the differences between the applicable civil law, the tax rules of your home country and those of each Spanish autonomous community, it is wise to plan your estate with a notary and a tax adviser who know both countries.
5. What health cover for British and American retirees in Spain?
Spain's health system is well regarded. It offers universal coverage and recognised primary care. According to the OECD, life expectancy reached 84 years in 2024, one of the highest in the European Union. So how do you get this cover when you retire to Spain?
As in most European countries, the public and private sectors exist side by side:
- If you choose the private system, you will generally have a wider choice of doctors and shorter waiting times. That does not guarantee better care than in the public sector.
- If you choose the public system, you will have broad coverage including GP care, specialist consultations on referral and hospital stays.
Our guide to healthcare in Spain explains in more detail how the public and private sectors work.
Part-year stays in Spain: the EHIC or GHIC
If you stay in Spain temporarily without moving your main home there, the European Health Insurance Card (EHIC) for EU residents, or the UK Global Health Insurance Card (GHIC) for UK residents, is essential. It gives you access to medically necessary care from Spanish public healthcare professionals and facilities, on the same terms as local patients.
This does not mean all care is free. Depending on the treatment, you may have to pay part of the cost or pay upfront. The card does not cover private facilities or medical repatriation either, and some planned treatments must be arranged in advance.
The card is individual and in your name, so every member of the household needs their own. A UK GHIC is free and lasts up to 5 years; the validity of an EHIC depends on the EU country that issues it.
Apply well before you leave: once approved, a UK GHIC should arrive within 15 working days.
- UK residents: apply on the official NHS website, where the card is free (avoid unofficial sites that charge a fee);
- EU residents: apply to your national health insurer or health service;
- US residents: there is no equivalent card, and Medicare generally does not cover care outside the United States;
- if you are not covered by any of these schemes, take out travel or private health insurance for your stays.
If you need care without your card, or your new card has not arrived, you can get a provisional replacement certificate (PRC). It gives the same rights as the card for a limited period.
Living in Spain permanently: registering with Spanish social security
If you live in Spain permanently and receive a UK State Pension, or a state pension from another EU country, without a Spanish pension, you may be entitled to healthcare funded by that country through the S1 form, formerly called the E121.
Here are the steps:
- Ask for the S1 form from the body responsible for your healthcare (for a UK State Pension, NHS Overseas Healthcare Services, by phone).
- Register it at the provincial office of the Instituto Nacional de la Seguridad Social for your Spanish address.
- Then register with the health service of your autonomous community.
- Ask for your tarjeta sanitaria individual, the card that gives you access to the Spanish public health system.
The procedure must cover each beneficiary moving to Spain. Once registered, you will receive care under the same rules as people insured in Spain. If you also receive a Spanish pension that gives you healthcare rights, Spain generally becomes the country responsible for your cover.
The system may work differently from what you are used to. Each patient is attached to a health centre and assigned a family doctor, much like a GP in the UK. This doctor handles routine care and refers patients to public-sector specialists.
Public care is generally provided directly, with no bills to claim back. Some costs, however, are covered little or not at all, in particular:
- part of the cost of prescription medicines;
- most routine dental care;
- glasses and other optical costs;
- some paramedical services.
Waiting times can also be longer for some specialist appointments or non-urgent operations.
Do you need private health insurance?
Private insurance is not compulsory when you are properly registered in the Spanish public system. It can still be useful to see some specialists faster, go directly to private hospitals or top up dental and optical cover. Without an S1, as is the case for American retirees, private insurance is usually needed; after a year of residence, you can apply to join the public system for a monthly fee (the Convenio Especial).
Spanish private health insurance does not always work like the cover you may have at home. Many policies give access to a set network of doctors, clinics and hospitals. Some offer full cover within that network, while others charge a co-payment for each visit.
The premium depends heavily on age, health, medical history, the cover chosen and whether there are co-payments. For a retiree, a general estimate of €50 to €100 a month is therefore too broad to rely on. It is best to ask for several quotes and check the exclusions, waiting periods and age limits. Our article on health insurance in Spain details the criteria to compare.
Good to know:
- If your home country remains responsible for your healthcare, you may keep access to care there. For example, UK nationals who were living in the EU on or before 31 December 2020 and hold a registered UK-issued S1 do not pay for NHS treatment when visiting England.
- During a temporary stay in another European country, use the EHIC issued by the body responsible for your healthcare. With a registered UK S1, you can get a UK-issued GHIC or EHIC for travel.
- Taking out international health insurance can give extra protection in some situations. Before signing up, check that it does not duplicate the rights opened by your S1 form or your private insurance.
For the detailed steps, see our practical guide to health cover for retirees in Spain.
6. Where to retire in Spain?
The Costa Blanca, Valencia, Andalusia and the Canary Islands are among the best-suited places to retire in Spain. The choice depends on your budget, the climate you want, how close you need to be to healthcare and whether you want a big city, a seaside resort or a quieter town.
The Costa Blanca: a setting suited to retirees
The Costa Blanca attracts retirees looking for sun, the sea and human-scale towns. Alicante-Elche airport also has many direct flights to the UK and northern Europe.
Alicante is a good choice if you want to keep an urban lifestyle. The city has shops, transport, healthcare facilities and a wide cultural offer, while opening directly onto the Mediterranean.
Further south, Torrevieja has more of a seaside feel and a large international population. In the north of the province, Dénia, Jávea and Calpe appeal more to retirees looking for a residential setting and a less built-up coastline.
Property prices can vary widely between central Alicante, the most sought-after resorts and inland towns. Our guide to living on the Costa Blanca compares its main towns.
Valencia: city life by the sea
Valencia offers a good balance between the services of a big city and the easy Mediterranean way of life. It has beaches, a lively historic centre, a well-developed transport network and many healthcare facilities.
The city can suit retirees who want to keep going out, get around without a car and enjoy an active cultural life. It is also easier to get to grips with than Madrid or Barcelona because of its more moderate size.
Choosing the neighbourhood is key. Central areas are livelier and generally more expensive, while outer districts and nearby towns offer more peace and sometimes larger homes.
Andalusia and the Costa del Sol: sunshine and a way of life
Andalusia suits retirees drawn to a sunny climate, a friendly pace of life and a wide variety of places. You can choose a big city, a coastal resort or an inland village.
Málaga is especially attractive for people who want to stay close to an international airport, medical services and a rich cultural life. Costa del Sol towns such as Estepona, Mijas or Fuengirola have a more residential feel, but see more tourists and more pressure on property prices.
Seville, Granada, Cadiz and Almería offer very different settings. Before choosing, take into account the intense summer heat, especially in inland cities. Our guide to living in Andalusia helps you explore these options.
Madrid and Barcelona: a resolutely urban retirement
Madrid and Barcelona are not the cheapest places in Spain, but they meet the needs of retirees who value transport, culture, specialist hospitals and frequent flights to the UK, northern Europe and the United States.
Living in Madrid gives you a particularly rich cultural life and a vast transport network. The capital is, however, far from the sea, with hot summers and colder winters than the Mediterranean regions.
Barcelona combines the advantages of a major city with the Mediterranean on its doorstep and the French border nearby. On the other hand, housing is expensive and some neighbourhoods are very busy with tourists.
To keep costs down while staying close to these cities, it can be worth looking at towns on their outskirts, as long as you check transport and access to healthcare.
The Canary Islands: mild weather all year round
The Canary Islands are a good option for retirees looking for fairly mild temperatures, including in winter. Tenerife and Gran Canaria have the most complete services, while the smaller islands offer a quieter setting.
Tenerife lets you choose between the tourist areas of the south and the greener north. Gran Canaria also offers a good balance between city life, beaches and natural landscapes.
The distance from mainland Europe is the main point to plan for. Going home always means a longer flight than from the mainland, which can become a constraint for keeping up regular family ties or arranging some medical care. The cost and availability of flights should therefore be included in your yearly budget.
What to check before choosing a town
A place that charms you on holiday is not necessarily suited to everyday life all year round. Before buying a flat or a house for your retirement, look in particular at:
- the purchase price or rents;
- how close a health centre, a hospital and a pharmacy are;
- shops open all year round;
- public transport and whether you need a car;
- flights to your home country;
- the climate in summer and in winter;
- how hilly and accessible the neighbourhood is;
- tourist activity in high season;
- community fees and local taxes.
If possible, rent a home for several weeks, ideally out of season, before making a final choice. This trial period lets you assess the neighbourhood, getting around, any nuisances and real access to the services you will need day to day.
Thomas Rouer is the founder of Alveo Search and the CEO of the Alveo group. Based in Spain for almost ten years, he develops property services designed for the specific needs of foreign buyers.
His expertise covers every aspect of buying property in Spain: understanding the market, searching for and selecting properties, negotiation, financing, paperwork, tax and securing the purchase process.
Our resources for buying in Spain